Fiduciary Financial Advisor Fees: Fee-Only vs. Fee-Based Models and AUM Pricing
Understand how fiduciary financial advisor fees are calculated, compare fee-only versus fee-based models, review standard AUM fee breakdowns, and spot hidden portfolio costs.
The Fiduciary Standard Versus the Suitability Standard
A fiduciary is legally required to manage money or property for someone else's benefit rather than their own (Source 1). Under the fiduciary standard, financial advisors must act in the best interests of their clients at all times, providing prudent advice and eliminating or fully disclosing any potential conflicts of interest (Source 1). This legal obligation applies continuously throughout the professional relationship.
In contrast, non-fiduciary brokers and sales reps operate under the suitability standard, overseen by regulatory authorities like the Financial Industry Regulatory Authority (FINRA). The suitability standard requires only that a recommended product be appropriate for the client's financial situation at the moment of sale. Under suitability rules, an advisor may legally recommend a product that pays them a higher commission over a less expensive alternative, provided the higher-cost option meets basic suitability criteria. Understanding this legal distinction is fundamental when analyzing fiduciary financial advisor fees.
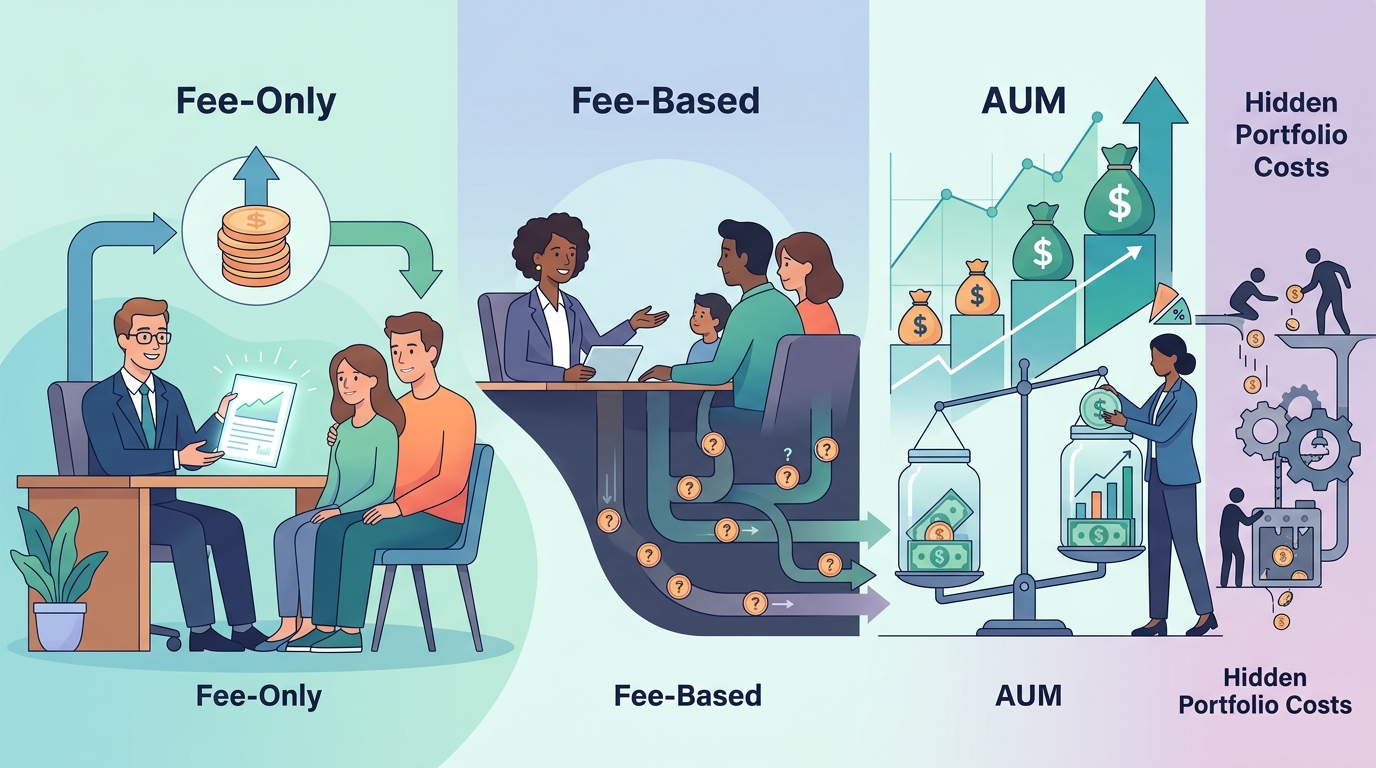
Fee-Only vs. Fee-Based Advisors: Core Structural Differences
When comparing a fee only vs fee based advisor, consumers often confuse the terminology because the phrases sound almost identical. However, the regulatory compensation structures differ substantially:
- Fee-Only Advisors: Paid exclusively by the client through direct billing (hourly, flat fee, subscription, or percentage of assets). Fee-only professionals and their firms accept no commissions, kickbacks, soft-dollar arrangements, or 12b-1 mutual fund distribution fees from third parties.
- Fee-Based Advisors: Paid by the client but may also earn third-party commissions from selling specific financial products, insurance policies, annuities, or mutual funds. This dual structure creates potential conflicts of interest, as recommendations might generate third-party compensation.
Selecting between these compensation models impacts total account costs and shapes the objectivity of investment recommendations. Fee-only firms are designed to minimize structural sales incentives, while fee-based firms allow advisors to act as both a fiduciary investment adviser and a commission-compensated broker depending on the transaction type.
Assets Under Management (AUM) Fee Structure Breakdown
The most common pricing framework among registered investment advisors is the Assets Under Management (AUM) fee model. Under an AUM structure, the advisor charges a percentage of the total investment portfolio value managed on behalf of the client. The national average wealth management fee percentage generally sits around 1.00% annually for account balances around $1 million, though fees typically scale down as portfolio size increases.
Advisors usually calculate AUM fees using a tiered standard rate schedule. As an account balance crosses predefined threshold boundaries, higher tranches of wealth are billed at progressively lower percentage rates. Below is a representative custom standard tier table derived from industry fee disclosures and regulatory filings:
| Account Balance Tier | Typical Annual AUM Fee Rate | Estimated Annual Cost |
|---|---|---|
| First $500,000 | 1.00% to 1.25% | $5,000 - $6,250 |
| $500,000 to $1,000,000 | 0.75% to 1.00% | $6,250 - $10,000 (cumulative) |
| $1,000,000 to $3,000,000 | 0.60% to 0.80% | $10,000 - $26,000 (cumulative) |
| $3,000,000 to $5,000,000 | 0.45% to 0.60% | $26,000 - $38,000 (cumulative) |
| Over $5,000,000 | 0.25% to 0.50% | Custom institutional pricing |
An aum fee structure breakdown shows that larger account balances benefit from economies of scale. Billing typically occurs quarterly in advance or in arrears, calculated using either the average daily balance or the end-of-quarter market value. Investors must review whether AUM fees cover only portfolio management or include comprehensive financial planning services.
Alternative Advisory Pricing Models: Flat Fees, Hourly, and Subscriptions
Investors seeking specific advice without committing an entire portfolio to an percentage-based management model can utilize alternative pricing structures. These options help avoid proportional fee growth as account balances rise over time.
- Flat or Fixed Project Fees: Clients pay a single fixed fee for a defined deliverable, such as a one-time comprehensive financial plan or estate plan review. Standard market fees range from $1,500 to $7,500 depending on complexity.
- Hourly Billing: Advisors bill directly for time spent on analysis, meetings, and implementation. Hourly rates across industry surveys typically range between $200 and $500 per hour.
- Subscription or Monthly Retainer: Common among younger investors or early-stage wealth builders, clients pay a set monthly or quarterly fee (e.g., $100 to $500 monthly) for ongoing advice and periodic strategy updates.
Hidden Portfolio Costs and Underlying Platform Fees
The fee paid directly to an advisor is only one layer of the total cost of wealth management. Portfolios incur underlying product, platform, and execution fees that do not appear on an advisor's primary invoice.
- Expense Ratios: Mutual funds and exchange-traded funds (ETFs) charge internal management fees. Passive index ETFs generally carry expense ratios between 0.03% and 0.20%, whereas actively managed mutual funds may charge 0.50% to 1.25% annually.
- Custodian Platform Fees: Custodians (such as Charles Schwab, Fidelity, or BNY Mellon Pershing) maintain accounts and process transactions. They may charge account maintenance fees, wire fees, or paper statement charges.
- Trading Commissions and Bid-Ask Spreads: While stock and ETF trades are frequently commission-free at major custodians, certain fixed-income securities, mutual funds, or international assets incur transaction charges.
- Third-Party Manager Fees: If an advisor delegates portfolio management to a separate account manager (SMA) or turnkey asset management program (TAMP), additional sub-advisory fees ranging from 0.15% to 0.50% may apply.
How to Verify Advisory Fees Using Form ADV Part 2A
Every Registered Investment Advisor (RIA) must file SEC Form ADV with regulatory authorities. Form ADV Part 2A—commonly called the Firm Brochure—is a primary legal document written in narrative format that details firm practices, fee schedules, and potential conflicts of interest.
To verify an advisor's fee disclosures, locate Form ADV Part 2A using the SEC Investment Adviser Public Disclosure (IAPD) search tool or FINRA BrokerCheck. Review these key items inside the document:
- Item 5 (Fees and Compensation): Outlines standard fee schedules, payment methods, bill timing (advance vs. arrears), and whether fees are negotiable.
- Item 10 (Other Financial Industry Activities and Affiliations): Discloses whether the firm or its personnel are affiliated with broker-dealers, insurance agencies, or investment funds that generate indirect income.
- Item 12 (Brokerage Practices): Details custodian relationships, trade aggregation practices, and potential soft-dollar arrangements.
Evaluating the Total Cost of Professional Financial Advice
To accurately evaluate financial advisory services, investors should calculate the total expense ratio of their portfolio, combining advisory fees, internal fund costs, and platform charges. For instance, a 1.00% AUM advisory fee paired with 0.60% underlying mutual fund fees yields a combined annual drag of 1.60% on portfolio growth.
By requesting a complete written cost breakdown and verifying terms within Form ADV Part 2A, investors can ensure their advisor adheres to a clear fiduciary standard (Source 1) while keeping cumulative wealth management expenses aligned with long-term financial goals.
What is the key legal difference between a fiduciary and a non-fiduciary advisor?
A fiduciary is legally required to manage money or assets for the client's benefit rather than their own, putting the client's best interests first (Source 1). Non-fiduciary advisors operating under the suitability standard must only ensure recommendations are appropriate for the client at the time of sale.
Does a fee-only financial advisor charge commissions?
No. Fee-only financial advisors are compensated directly by their clients through flat fees, hourly rates, subscriptions, or asset-under-management percentages. They accept no sales commissions or third-party compensation.
Where can I locate an advisor's Form ADV disclosure brochure?
You can view and download Form ADV Part 2A free of charge using the SEC Investment Adviser Public Disclosure (IAPD) website or FINRA BrokerCheck portal by searching the firm's name or CRD number.
Sources
- What is a Fiduciary Financial Advisor? — Consumer Financial Protection Bureau
This article is for general information only and is not professional advice. Figures come from public sources and change over time; check the official source before you act.
More from Daily Facts Wire
- 5 Lifeline Phone Application Mistakes That Stop Your Monthly Benefits
- 7 Income Rules That Qualify You for a Free Smartphone Today
- The 4.5GB Smartphone Data Secret Millions Miss Each Month
- Get Your Free Smartphone Through Federal Lifeline and Meta Promo Rules
- 4 Costly Mistakes People Make Claiming Free Phones On Facebook
- The $35 Hidden Activation Fee Inside Free Meta Phone Offers